


Purchasing
Take the First Step Towards Owning Your Dream Home
Instant Results
Take 3 Minutes
No Credit Pull
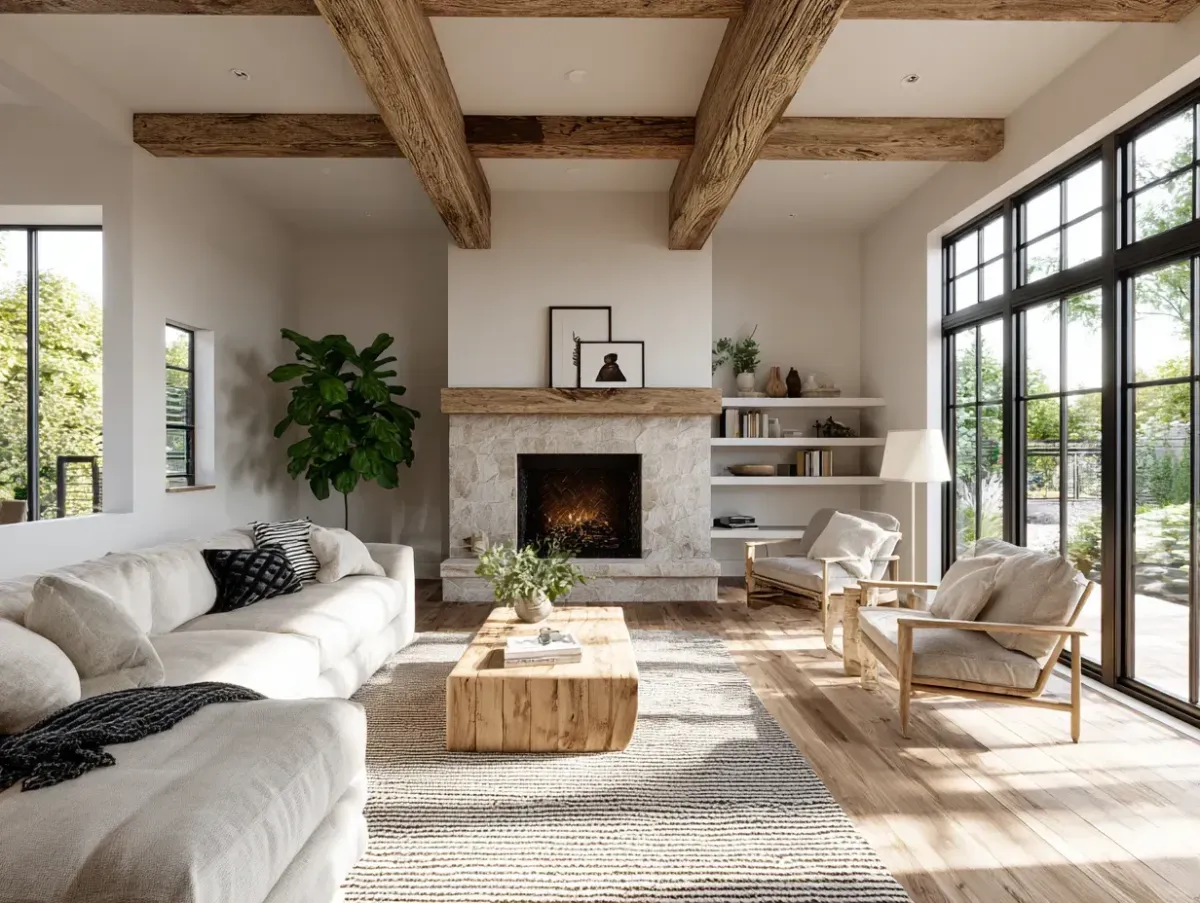
First-Time Homebuyer Tips
Navigating the home-buying process for the first time can be overwhelming. Here are some essential tips to get you started on the right foot:
1. Start by setting a
budget.
2. Get pre-approved for a mortgage.
3. Research neighborhoods and schools.
4. Work with a trusted real estate agent.
Have a Mortgage Question?
We have the answers you need.
How do I qualify for a loan?
How do I qualify for a loan?
Qualifying for a loan depends on several factors including your credit score, income, employment history, and debt-to-income ratio. We evaluate these factors to determine your eligibility and the best loan options for you.
How can I improve my chances of getting approved for a loan?
How can I improve my chances of getting approved for a loan?
Answer: Improving your credit score, reducing existing debts, and ensuring a stable income can enhance your loan approval chances. We can provide personalized advice based on your financial situation. The best way to set yourself up for success is to get pre-approved early so we can look at your situation and give you a plan custom fit to your needs.
Do I need 20% down to buy a home?
Do I need 20% down to buy a home?
Answer: No, you do not need 20% down to buy a home. There are loan programs available that allow for lower down payments, even as little as 3% down for qualified buyers. When you put less than 20% down you will have what is called PMI (private mortgage insurance). PMI is an amazing tool for homebuyers and is not something to be afraid of. We can help you explore these options based on your financial situation.
Can I get a loan if I have low credit?
Can I get a loan if I have low credit?
Answer: Yes, it's possible to get a loan with low credit, though the options and interest rates may vary compared to those with higher credit scores. We offer a range of products that cater to different credit profiles and can provide guidance on how to improve your credit to qualify for better terms.
What is PMI, and is it bad?
What is PMI, and is it bad?
Answer: PMI, or Private Mortgage Insurance, is a type of insurance that lenders require from borrowers who put down less than 20% on a home purchase. It protects the lender in case of default. PMI is not a bad thing; in fact, it is a very powerful homebuying tool. With decent credit PMI could be very cheap and allows buyers who cannot afford a 20% down payment to still purchase a home.
Didn't find your answer? Reach out to us, we're happy to help.
Megan Higgs
Sales Manager | Loan Officer
NMLS# 77202
Branch NMLS# CL-2499521 | 2499521 | 1047981
Corporate License #1359687
5727 Baker Way NW, Suite 102 Gig Harbor, WA 98332
+13607313464
Branch Phone: 253-649-4041